Australia’s new merger reforms commenced on 1 January 2026 and mark the most significant overhaul in how mergers and acquisitions are regulated in decades.
The changes introduced a mandatory and suspensory notification administrative regime, representing a significant departure from the longstanding voluntary informal clearance process with a judicial enforcement model.
Mandatory notification regime
The Competition and Consumer Act 2010 (Cth) (CCA) prohibits a corporation from directly or indirectly acquiring shares or assets where the likely effect of the acquisition would be a substantial lessening of competition in a market.
Notifiable acquisitions must not close or be put into effect until after they have been approved by the ACCC (or the Competition Tribunal, on review). A merger will be permitted to proceed unless the ACCC is satisfied that the acquisition would, in all circumstances, have the effect or likely effect of substantially lessening competition (SLC) in any market. Consistent with global trends, the proposed amendments clarify that SLC can result from creating, strengthening or entrenching a position of substantial market power.
The consequences of not notifying are significant:
- the transaction is voidable (i.e. it may be voided if the Court orders, on application by the ACCC to the Federal Court); and
- substantial penalties and other orders can also apply.
Notifiable transactions and thresholds
An acquisition must be notified where each of the following are satisfied:
- it involves a person acquiring assets or ‘control’ of an entity through a share sale;
- it meets the monetary thresholds or is subject to a specific ministerial designation; and
- the target is ‘connected’ with Australia.
There is the ability for parties to seek a waiver from the ACCC and certain exemptions may apply.
Importantly, it is no longer relevant whether an acquisition is likely to raise a potential competition concern, e.g., due to combined market shares. If a deal meets the monetary and other thresholds, parties must notify the ACCC regardless.
Understanding ‘control’ under the new ACCC merger rules
In the case of a share sale, notification is required if a transaction gives the acquirer ‘control’ of a body corporate. This concept is defined broadly and will apply in any case where either:
- you are acquiring a majority stake
- you (either alone or together with associates) are in a position to practically determine or influence the outcome of decisions about the financial and operating policies of the company (noting there is a carve-out in certain circumstances where there is an agreement that provides minority shareholder protection rights).
There are exemptions for acquisitions of shares where:
- the acquirer does not, immediately post‑transaction, control the target; or
- the acquirer already controlled the target pre‑transaction.
A safe harbour applies to listed companies (or unlisted companies with more than 50 members (widely held companies)) where the acquirer obtains less than 20% voting power or already has over 20% and is acquiring additional shares.
Acquisitions falling within the following scenarios must be notified if they meet the monetary thresholds:
- Acquisition of shares in a company that is not a Chapter 6 entity or listed on a foreign approved stock exchange, where the acquirer’s voting power increases from <20% to >20%. However, to ensure that only acquisitions of material voting power over the entity are captured, when calculating an acquirer’s voting power, the votes of entities which are considered associates only because they have entered into, or have proposed to enter into, an agreement with the person for minority shareholder protection rights should be disregarded.
- Acquisition of shares in any body corporate (listed or unlisted, foreign or domestic), where the acquirer’s voting power moves from >20% but <50%, to an end point that is >50%. In calculating an acquirer’s voting power, the votes of entities who are considered associates only because they have entered into, or have proposed to enter into an agreement with the person for minority shareholder protection rights are also to be disregarded.
- Where the target is a Chapter 6 entity, and:
- The principal party already controls the target, and the voting power moves from < 20% to > 20%.
- The principal party does not control the target immediately before or after the acquisition, and the voting power moves from < 20% to >50%.
In some cases, minority stakes (under 50%) will offer sufficient influence to be considered a controlling interest. There is uncertainty about how this test applies to companies subject to shareholder agreements, joint venture agreements, or similar documents that give all members joint influence over the company.
The uncertainty surrounding the control test means that it is recommended you seek advice about notification, even for minority stakes, if your deal meets the financial thresholds.
Merger thresholds – notification revenue and value
The primary test for notification is based on the revenue of the parties or total transaction value. Lower thresholds apply for corporate groups with more than $500 million turnover in Australia. Revenue refers to revenue in Australia in the last 12-month reporting period, as defined under applicable accounting standards.
Recent amendments have introduced higher thresholds for acquisitions that do not represent all, or substantially all, of the assets of a business.
When assessing these revenue thresholds, the turnover of the firms as well as any ‘connected’ entities will be relevant. In simple terms, a connected entity of the acquirer captures:
- related bodies corporate of the acquirer;
- an entity that controls, or is controlled by, either alone or together with one or more associates, the acquirer;
- an entity that is under common control with the acquirer by another entity.
A person is considered an ‘associate’ of another person, in relation to a particular company if at least one of the following applies:
- Corporate relationships: both persons are in the same corporate group (e.g. they control each other or are controlled by the same parent entity).
- Agreements to influence: one person is acting, or plans to act together with the other person to influence the target entity’s financial and operating policies.
- Agreements to act in concert: one person is acting, or plans to act together with another person, to control or influence the target entity’s financial and operating decisions.
This language expressly ties the associate definition to relationships that involve controlling or influencing the target's financial and operating policies – in other words, relationships that could practically influence competition.
Express exceptions also apply, including due to minority shareholder protection rights, dividend-policy agreements and more. The Minister also has powers to determine classes of agreements, rights, or matters relevant to the associate analysis.
The combined revenue of merger parties (including relevant connected entities) on contract date is ≥$200 million and either:
- For the acquisition of shares:
- Revenue of target (including connected entities) is ≥$50 million;
- Transaction value is ≥$250 million (calculated as the greater of market value or consideration under sale agreement)
- For the acquisition of assets where the assets form all or substantially all assets of a business:
- Revenue of assets being acquired is ≥$50 million; or
- Transaction value is ≥$250 million (calculated as the greater of market value or consideration under sale agreement)
- For acquisitions of assets where the asset does not form all or substantially all assets of a business: transaction value is ≥$200 million (calculated as the greater of market value or consideration under sale agreement).
Note: Where the acquisition is of all, or substantially all, of the assets of a business, the amount to be calculated for the purposes of determining whether the monetary threshold has been met is the Australian revenue of the target to the extent that revenue is attributable to the business.
The acquirer (including connected entities) has revenue on contract date of ≥ $500 million and:
- revenue of the target (including connected entities) is ≥ $10 million (where the asset(s) form all or substantially all assets of a business); or
- transaction value is ≥ $50 million (calculated as the greater of market value or consideration under sale agreement), where the asset does not form all or substantially all assets of a business.
Note: Where the acquisition is of all, or substantially all, of the assets of a business, the amount to be calculated for the purposes of determining whether the monetary threshold has been met is the Australian revenue of the target to the extent that revenue is attributable to the business.
As well as thresholds that apply to the standalone revenue of a target business, there are also thresholds that apply to similar transactions undertaken over the last three years. These are either:
- if the combined revenue of the merger parties (including connected entities) is ≥$200 million and the cumulative revenue from acquisitions by the acquirer (including connected entities) in the past three years involving competitive goods or services is ≥$50 million
- if the combined revenue of the merger parties (including connected entities) is ≥$500 million and the cumulative revenue from acquisitions by the acquirer (including connected entities) in the three years before the contract date involving competitive goods or services is ≥$10 million.
When applying this three-year cumulative test, the following are excluded:
- transactions involving revenue of less than $2 million;
- share acquisitions where the acquirer has not begun, or cannot begin to control, the target body corporate
- assets that have subsequently been divested or disposed of, or
- if the acquisition is of an asset, the acquisition does not have the effect that a person will, or can, acquire all, or substantially all of the assets of a business, and the market value of the asset is <$2 million.
There is a range of exemptions and safe harbours that apply to particular types of transactions – for example: acquiring less than 20% of shares in a listed company, ordinary course-of-business transactions (including those involving land, but excluding patents), deals where the target’s Australian revenue is under $2 million, and other financial market exemptions
Other exemptions may apply to internal restructures or sale and leaseback arrangements, but legal advice should always be sought to confirm eligibility.
Non-competes in relation to the sale of a business are exempt from the prohibition on cartel conduct if they are solely for the purpose of protecting the goodwill acquired by the purchaser.
However, under the new reforms the ACCC now has power to declare that the exemption does not apply if it finds a non-compete or other sale restraint is not necessary to protect the purchaser’s goodwill.
Merger notification process and filing fees
There is a choice of three forms:
- A waiver notification form – which is suitable for straightforward transactions that do not raise any competition risks (these can only be filed from 1 January 2026).
- A short form notification – which is suitable for transactions that may involve competitors (or a supplier and customer), but where there is unlikely to be any substantial lessening of competition concern.
- A long form notification – which is for transactions that are more complex or are likely to require more detailed consideration by the ACCC.
The forms are available from the ACCC website. In all cases, the ACCC can require more detailed information and supporting documents from merger parties.
A merger will be permitted to proceed unless the ACCC is satisfied that the acquisition would, in all circumstances, have the effect or likely effect of SLC in any market. Consistent with global trends, the proposed amendments clarify that SLC can result from creating, strengthening or entrenching a position of substantial market power. This may increase scrutiny of smaller transactions undertaken by large players or market leaders.
The timeframes associated with the process vary depending upon the complexity of the deal. The ACCC expects that 80% of deals will be processed within 20 business days.
In summary:
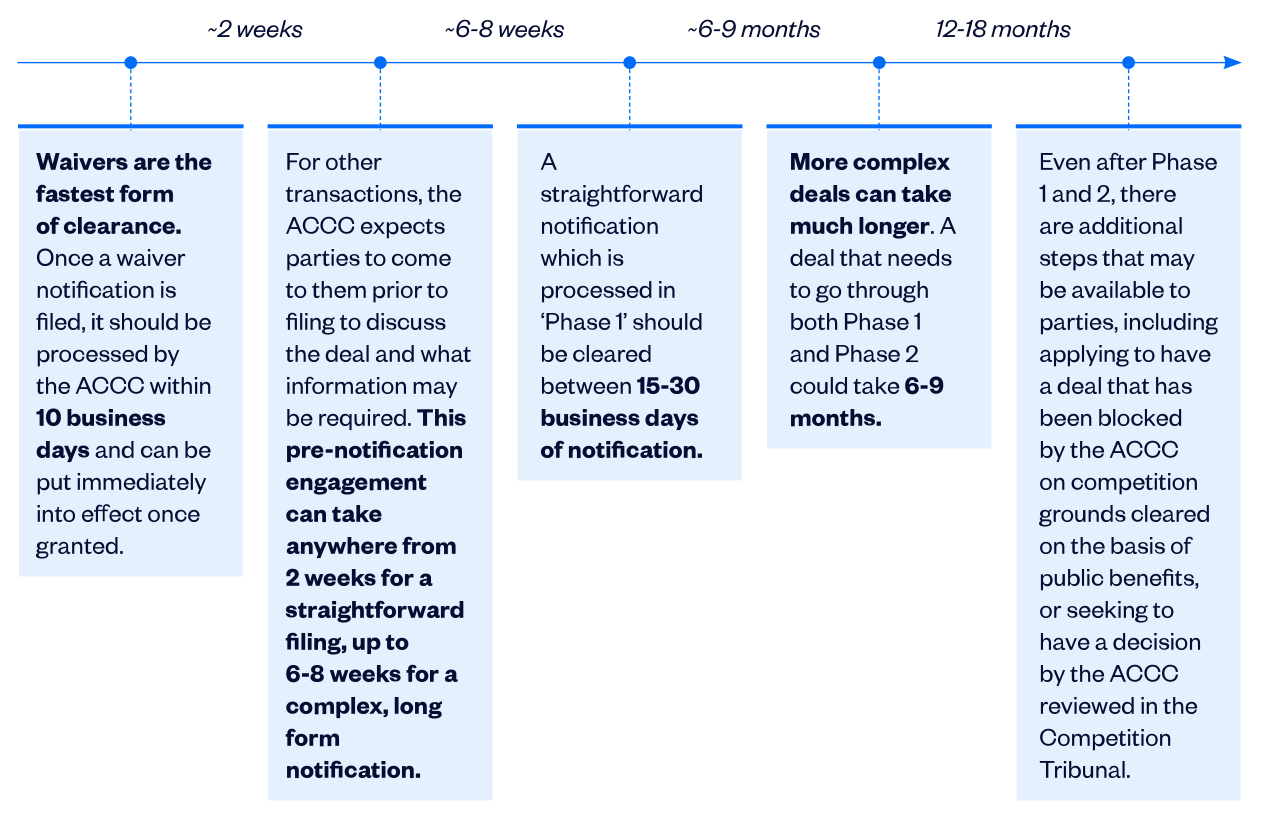
Parties also cannot complete or put a deal into effect until 15 days after the ACCC publishes its reasons in relation to the notification (although parties can do so immediately if they get a waiver).
Fees
The filing fees relating to notification of acquisitions under the new system are:
- $8,300 per notification waiver application;
- $56,800 per notification of a proposed acquisition – the review of all notified mergers commences in Phase 1 and incurs a fee;
- an additional fee will be charged for mergers that proceed to Phase 2. If the greater of the sum of the market values or consideration receivable of all the shares and assets being acquired is:
- $50 million or less: the fee for Phase 2 review is $475,000;
- more than $50 million, but not more than $1 billion: the fee for Phase 2 review is $855,000; or
- more than $1 billion: the fee for Phase 2 review is $1,595,000.
This fee must be paid within 7 business days commencing from the day the ACCC advises the notifying party that the notification is subject to Phase 2 review;
- $401,000 per Public Benefits application – an additional fee will be payable if a notifying party makes an application for a public benefits review; and
- the costs associated with Tribunal reviews will be subject to separate government decisions and consultation.
An exemption will be available for acquisitions made by small business entities as defined by the Income Tax Assessment Act 1997, i.e. where they carry on a business in the current year and the aggregated turnover for the previous year was less than $10 million or the aggregated turnover for the current year is likely to be less than $10 million.
The government proposes to index the fees annually at the beginning of each financial year.
The proposed fees represent a significant departure from the current regime where the operational cost of merger control incurred by the ACCC is funded through consolidated revenue by taxpayers (consistent with regimes in other jurisdictions), As foreshadowed in the consultation paper, the revenue generated from the proposed filing fees are intended to cover the ACCC’s estimated operational costs to be devoted to each level of review and recognise that significant additional resources will be required to administer the new regime, taking into the number of reviews to be undertaken per year.